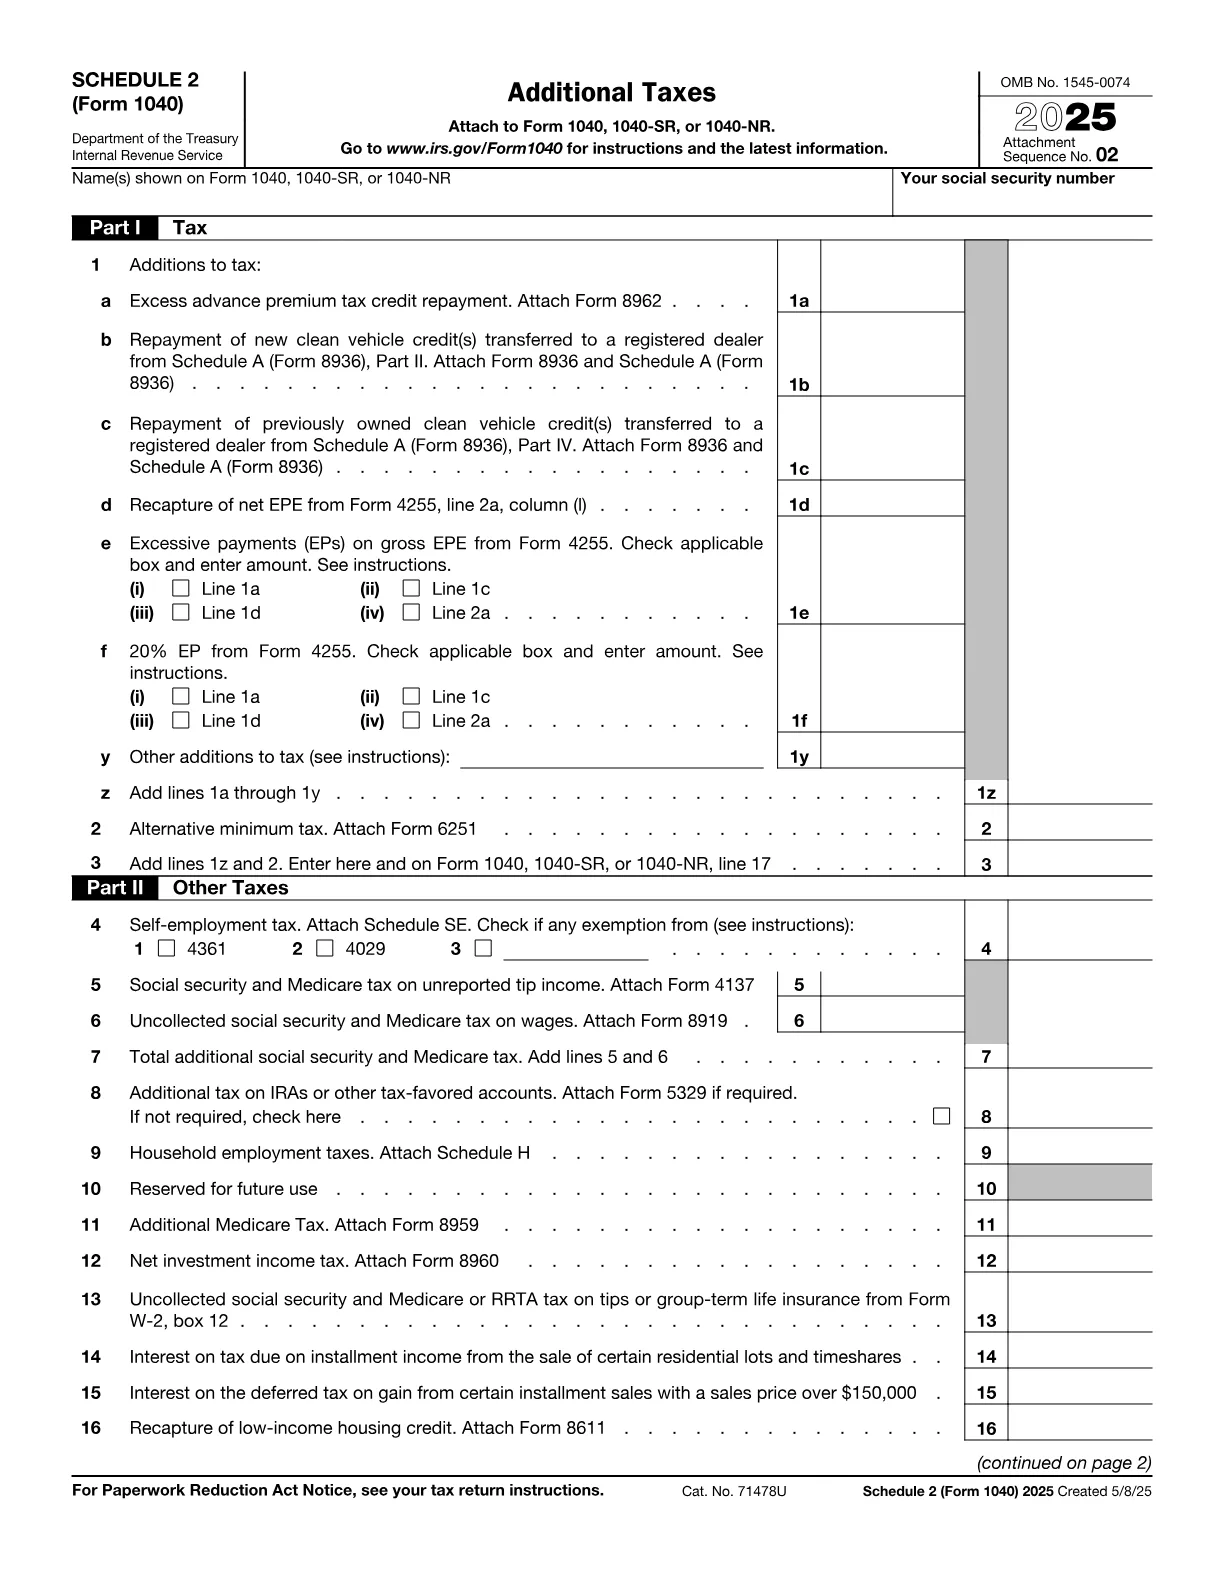
Schedule 2 holds the taxes that can't be entered directly on Form 1040: Part I (additions to tax and the alternative minimum tax) goes to Form 1040, line 17, and Part II (self-employment tax, household employment taxes, the additional tax on early retirement withdrawals and others) goes to line 23. Tap any line on the form to see what goes there, where the number comes from, and the practice returns that fill it in.
Every line, explained
No line matches that. Try a line number like 17c, or a word like Medicare.
Part I: Tax
1aExcess advance premium tax credit repayment
If the advance payments of the premium tax credit sent to a Marketplace insurer were more than the credit the taxpayer actually qualifies for, Form 8962 figures how much has to be paid back. The repayment from Form 8962, line 29, goes here. It can apply even if someone else enrolled the taxpayer.
Where it comes from: Form 8962, built from Form 1095-A.
Practice returns: none use this line yet. Request one.
1b, 1cRepayment of clean vehicle credits transferred to a dealer
A buyer who transferred the clean vehicle credit to a registered dealer to lower the price at the time of sale may have to pay it back if they no longer qualify. Line 1b is for a new clean vehicle, line 1c for a previously owned one.
Where it comes from: Schedule A (Form 8936), Part I, line 4a, with Part II (new) or Part IV (previously owned).
Practice returns: none use this line yet. Request one.
1d to 1fElective payment recapture and excessive payments from Form 4255
Recapture of a net elective payment election (EPE) amount (1d), excessive payments on a gross EPE (1e), and the 20% excessive payment amount (1f). Lines 1e and 1f have checkboxes for the Form 4255 line the amount comes from. They come up only when a credit was taken as an elective payment and later recaptured or found to be too much.
Where it comes from: Form 4255.
Practice returns: none use this line yet. Request one.
1yOther additions to tax
Additions with no line of their own, each identified by a code from the instructions, such as "ARPCR" for recapture of the alternative fuel vehicle refueling property credit.
Where it comes from: Forms 8911, 8933 and 4255.
Practice returns: none use this line yet. Request one.
1zAdd lines 1a through 1y
Total additions to tax.
Where it comes from: Lines 1a to 1y.
Practice returns: none use this line yet. Request one.
2Alternative minimum tax
The alternative minimum tax from Form 6251, line 11: a parallel tax with its own rules that is owed when it comes out higher than the regular tax. For 2025 the AMT exemption is $88,100 ($137,000 married filing jointly or qualifying surviving spouse, $68,500 married filing separately), and it starts to phase out at $626,350 ($1,252,700 jointly).
Where it comes from: Form 6251.
Practice returns: none use this line yet. Request one.
3Add lines 1z and 2
Carried to Form 1040, line 17, where it is added to the regular income tax before credits.
Where it comes from: Lines 1z and 2.
Practice returns: none use this line yet. Request one.
Part II: Other taxes
4Self-employment taxNew for 2025
Social Security and Medicare tax on self-employment earnings, from Schedule SE, line 12. New for 2025, three checkboxes replace written notes for exemptions: box 1 for an approved Form 4361 (ministers) with no other self-employment income, box 2 for an approved Form 4029 (certain religious sects), and box 3 for other cases, such as notary fees ("EN"), exempt community income ("ECI") or coverage under a foreign social security agreement ("EAS").
Where it comes from: Schedule SE, line 12.
Practice returns that fill in this line (18):
- Business meals: 50%, 100%, or nothing on Schedule C
- Colorado: starting from federal taxable income with a Schedule C
- Consultant with a SEP-IRA
- Content creator with several income streams
- Freelance designer with a home office
- Independent contractor who expected a refund
- Iowa self-employed photographer: flat 3.8% tax and the school district surtax
- Minister with a housing allowance
- Mississippi self-employed painter: Schedule C, commuting miles, SE tax, QBI, and a state that builds its own AGI
- Montana fishing guide: federal taxable income without QBI
- Online seller with inventory
- Oregon: the federal tax subtraction and the 2025 kicker for a freelancer
- Partner with a K-1 and guaranteed payments
- Real estate agent (Schedule C, actual vehicle expenses)
- Rideshare and delivery driver (gig work)
- Six K-1s, a partnership exit, and Section 1231
- Small farm (Schedule F)
- Virginia self-employed: Schedule C, estimates, and the $4,000 Virginia529 deduction
5Social security and Medicare tax on unreported tip income
An employee who received $20 or more in tips in a month and did not report them all to the employer owes the employee share of Social Security and Medicare tax on the unreported tips. Noncash tips, such as tickets or passes, are not taxed this way.
Where it comes from: Form 4137.
Practice returns: none use this line yet. Request one.
6Uncollected social security and Medicare tax on wages
An employee whose employer did not withhold Social Security and Medicare tax, often a worker wrongly treated as an independent contractor, pays the employee share here. The tax is Form 8919, line 13; the wages go on Form 1040, line 1g.
Where it comes from: Form 8919.
Practice returns: none use this line yet. Request one.
7Total additional social security and Medicare tax
Lines 5 and 6 added together.
Where it comes from: Lines 5 and 6.
Practice returns: none use this line yet. Request one.
8Additional tax on IRAs or other tax-favored accounts
The additional tax on an early distribution from an IRA or retirement plan, plus the taxes on excess contributions, a missed required minimum distribution, and taxable Coverdell, 529 or ABLE distributions, all figured on Form 5329. If the only issue is an early distribution with code 1 correctly shown in box 7 of every Form 1099-R and no exception applies, skip Form 5329: enter 10% of the taxable amount and check the box.
Where it comes from: Form 5329, or Form 1099-R box 7.
Practice returns that fill in this line (3):
9Household employment taxes
Social Security, Medicare and federal unemployment tax for a household employee such as a nanny, housekeeper or caregiver. It applies if the taxpayer paid any one household employee $2,800 or more in cash wages in 2025, withheld federal income tax at the employee's request, or paid $1,000 or more in cash wages in any calendar quarter of 2024 or 2025.
Where it comes from: Schedule H.
Practice returns that fill in this line (1):
10Reserved for future useNew for 2025
Blank for 2025. Through 2024 this line held the repayment of the first-time homebuyer credit (Form 5405).
Where it comes from: Nothing goes here.
Practice returns: none use this line yet. Request one.
11Additional Medicare Tax
An extra 0.9% Medicare tax on wages and self-employment income above a threshold. Check Form 8959 if wages plus self-employment income were over $200,000 (single, head of household or qualifying surviving spouse), $250,000 (married filing jointly) or $125,000 (married filing separately). Additional Medicare Tax an employer withheld is a payment on Form 1040, line 25c.
Where it comes from: Form 8959, with Form W-2 boxes 5 and 6.
Practice returns that fill in this line (3):
12Net investment income tax
A tax on interest, dividends, capital gains, rents and other investment income for higher-income taxpayers. Check Form 8960 if Form 1040, line 11b, is more than $200,000 (single or head of household), $250,000 (married filing jointly or qualifying surviving spouse) or $125,000 (married filing separately).
Where it comes from: Form 8960.
Practice returns that fill in this line (3):
13Uncollected social security and Medicare or RRTA tax on tips or group-term life insurance
Tax the employer could not collect from the employee's pay, on tips or on group-term life insurance. The employer reports it on Form W-2, so it is copied here.
Where it comes from: Form W-2, box 12, codes A and B (tips) or M and N (group-term life insurance).
Practice returns: none use this line yet. Request one.
14, 15Interest on deferred tax from certain installment sales
Interest owed on the tax put off by reporting a sale on the installment method: line 14 for the sale of certain residential lots and timeshares (section 453(l)(3)), line 15 for installment sales with a sales price over $150,000 (section 453A(c)).
Where it comes from: Form 6252 and the interest computation.
Practice returns: none use this line yet. Request one.
16Recapture of low-income housing credit
Low-income housing credit claimed in earlier years that has to be paid back.
Where it comes from: Form 8611, line 14.
Practice returns: none use this line yet. Request one.
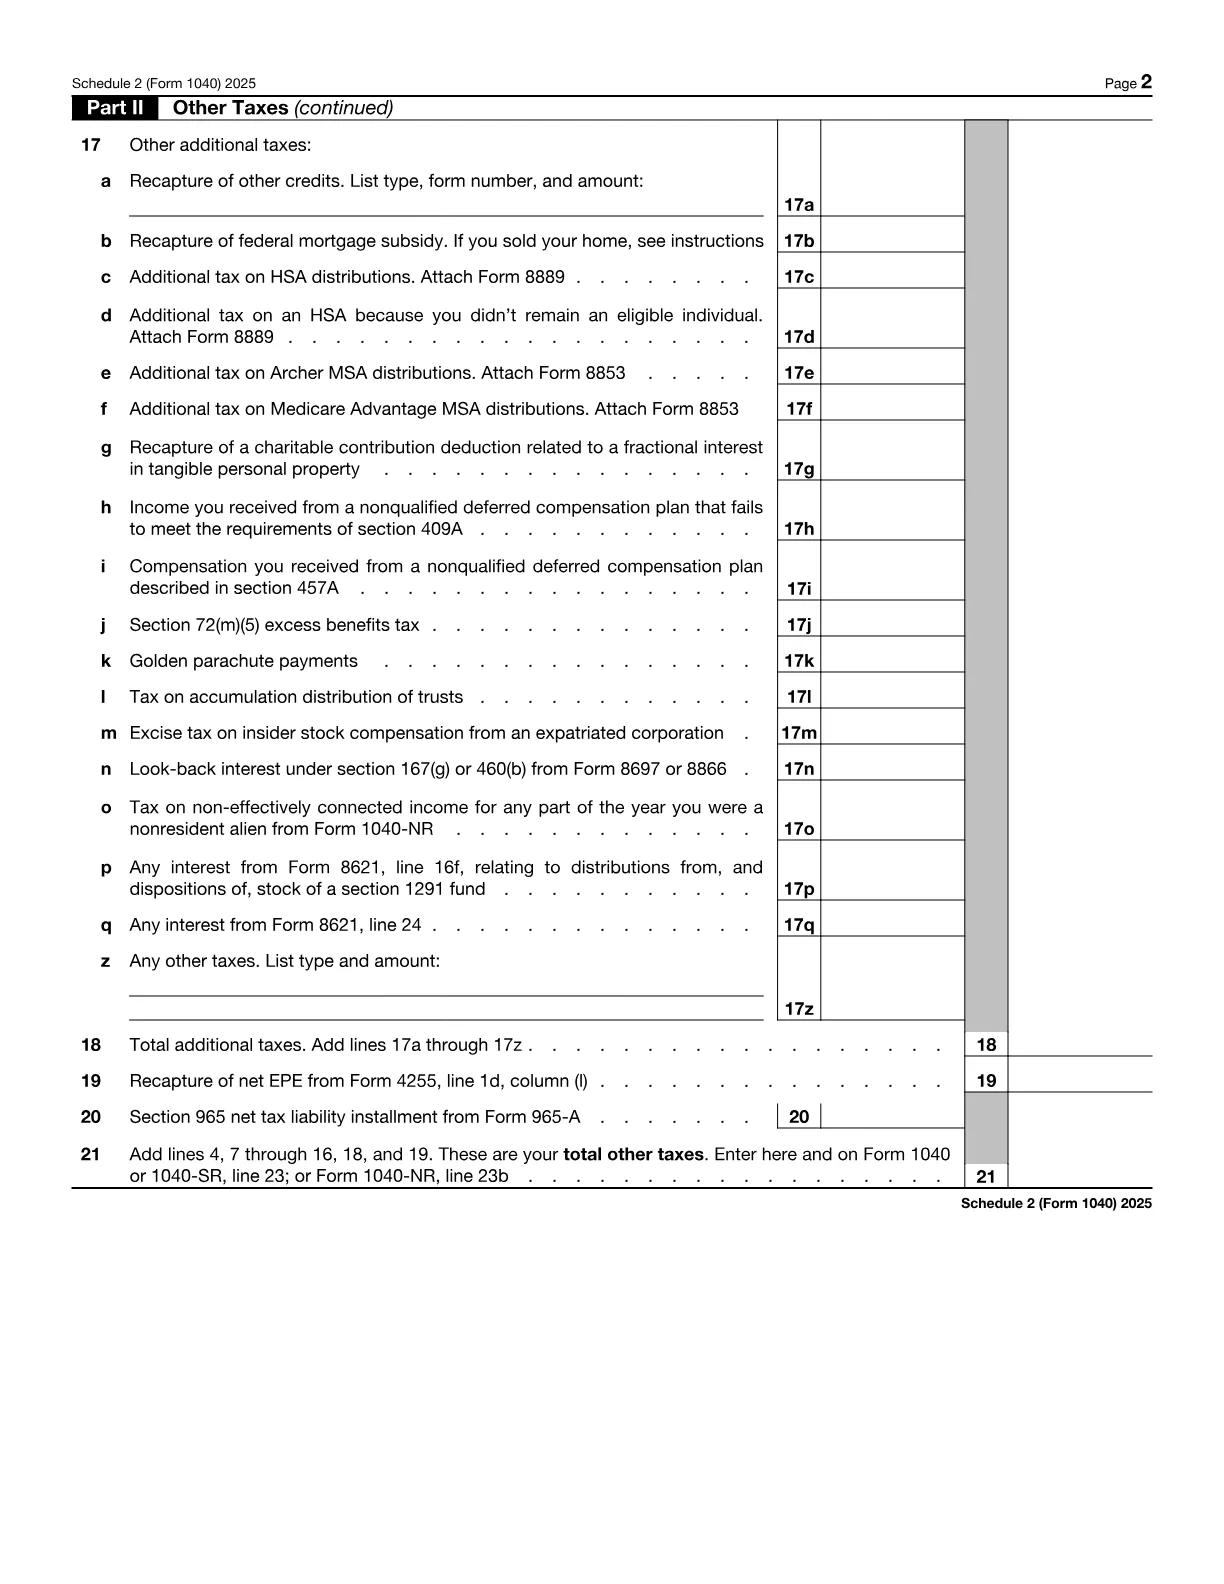
Part II, continued: Other additional taxes and the total
17aRecapture of other credits
Credits from earlier years that have to be paid back, listed by type, form number and amount with the codes in the instructions, for example "3468" for investment credit recapture from Form 4255, "NMCR" for the new markets credit and "ECCFR" for the employer-provided childcare facilities credit.
Where it comes from: Forms 4255, 8874 and 8882.
Practice returns: none use this line yet. Request one.
17bRecapture of federal mortgage subsidy
If the taxpayer sold a home in 2025 that was financed with a tax-exempt qualified mortgage bond, or claimed the mortgage interest credit on it, a recapture tax may be due.
Where it comes from: Form 8828.
Practice returns: none use this line yet. Request one.
17c, 17dAdditional tax on HSA distributions and on not remaining eligible
Line 17c is the additional tax on HSA distributions not used for qualified medical expenses (Form 8889, line 17b). Line 17d is the additional tax for not remaining an eligible individual during the testing period, which can follow a contribution made under the last-month rule (Form 8889, line 21).
Where it comes from: Form 8889, built from Form 1099-SA.
Practice returns that fill in this line (1):
17e, 17fAdditional tax on Archer MSA and Medicare Advantage MSA distributions
The additional tax on distributions from an Archer MSA (Form 8853, line 9b) or a Medicare Advantage MSA (Form 8853, line 13b).
Where it comes from: Form 8853.
Practice returns: none use this line yet. Request one.
17gRecapture of a charitable deduction for a fractional interest
Additional tax when a charitable deduction taken for giving a fractional interest in tangible personal property, such as part ownership of a painting, has to be recaptured. Pub. 526 explains when.
Where it comes from: Pub. 526 and the taxpayer's records.
Practice returns: none use this line yet. Request one.
17h, 17iNonqualified deferred compensation (sections 409A and 457A)
The additional tax on income from a deferred compensation plan that fails section 409A (17h), or on compensation from a plan described in section 457A (17i). In both cases the tax is 20% of the amount included in income plus an interest amount.
Where it comes from: Form W-2 box 12 code Z, or Form 1099-MISC box 15.
Practice returns: none use this line yet. Request one.
17jSection 72(m)(5) excess benefits tax
A tax under section 72(m)(5) on certain excess benefits from a retirement plan. It is rare; Pub. 560 explains when it applies.
Where it comes from: Pub. 560 and the plan's records.
Practice returns: none use this line yet. Request one.
17kGolden parachute payments
A 20% tax on an excess parachute payment. It is shown on Form W-2 with code K; if the payment came on Form 1099-NEC, the tax is 20% of the excess parachute payment in box 3.
Where it comes from: Form W-2 box 12 code K, or Form 1099-NEC box 3.
Practice returns: none use this line yet. Request one.
17lTax on accumulation distribution of trusts
Tax on a trust's distribution of income it held back in earlier years.
Where it comes from: Form 4970.
Practice returns: none use this line yet. Request one.
17mExcise tax on insider stock compensation from an expatriated corporation
The section 4985 excise tax on stock compensation held by insiders of a corporation that moved its tax home outside the United States.
Where it comes from: Section 4985 and the company's records.
Practice returns: none use this line yet. Request one.
17nLook-back interest under section 167(g) or 460(b)
Interest owed or refunded when actual results differ from estimates used in earlier years: on long-term contracts (Form 8697) or on property depreciated under the income forecast method (Form 8866).
Where it comes from: Form 8697 or Form 8866.
Practice returns: none use this line yet. Request one.
17oTax on non-effectively connected income
For someone who was a nonresident alien for part of the year, the tax on income not effectively connected with a US trade or business for that part of the year.
Where it comes from: Form 1040-NR.
Practice returns: none use this line yet. Request one.
17p, 17qInterest from Form 8621
Interest charges for shares of a passive foreign investment company (PFIC): on distributions from, and dispositions of, stock of a section 1291 fund (Form 8621, line 16f), and the interest from Form 8621, line 24.
Where it comes from: Form 8621.
Practice returns: none use this line yet. Request one.
17zAny other taxes
Taxes with no line of their own, listed by type and amount. The instructions name the prevailing wage and apprenticeship penalties from Form 4255 and a negative Form 8978 adjustment from a partnership audit.
Where it comes from: Forms 4255 and 8978.
Practice returns: none use this line yet. Request one.
18Total additional taxes
Lines 17a through 17z added together.
Where it comes from: Lines 17a to 17z.
Practice returns that fill in this line (1):
19Recapture of net EPE from Form 4255, line 1d
Recapture of a net elective payment amount related to the investment credit from Form 3468, Part IV.
Where it comes from: Form 4255, line 1d, column (l).
Practice returns: none use this line yet. Request one.
20Section 965 net tax liability installment
The current installment of tax on deferred foreign income under section 965, for a taxpayer who elected to pay it over several years. It is not added into line 21.
Where it comes from: Form 965-A.
Practice returns: none use this line yet. Request one.
21Total other taxes
Lines 4, 7 through 16, 18 and 19 added together, carried to Form 1040, line 23, and added to the tax after credits.
Where it comes from: The lines above.
Practice returns that fill in this line (27):
- Business meals: 50%, 100%, or nothing on Schedule C
- Changed jobs mid-year: excess Social Security tax
- Colorado: starting from federal taxable income with a Schedule C
- Consultant with a SEP-IRA
- Content creator with several income streams
- Early retirement withdrawal and the penalty
- Early Roth IRA withdrawal: contributions first, then earnings
- Freelance designer with a home office
- Household employer (the nanny tax)
- HSA over-contribution and a non-medical withdrawal
- Independent contractor who expected a refund
- Iowa self-employed photographer: flat 3.8% tax and the school district surtax
- Married couple, two backdoor Roths, two Forms 8606
- Minister with a housing allowance
- Mississippi self-employed painter: Schedule C, commuting miles, SE tax, QBI, and a state that builds its own AGI
- Montana fishing guide: federal taxable income without QBI
- Online seller with inventory
- Oregon: the federal tax subtraction and the 2025 kicker for a freelancer
- Partner with a K-1 and guaranteed payments
- Real estate agent (Schedule C, actual vehicle expenses)
- Rhode Island: the standard deduction and exemption phase-out for a high-earning couple
- Rideshare and delivery driver (gig work)
- Six K-1s, a partnership exit, and Section 1231
- Small farm (Schedule F)
- Sold the rental house: Section 1231, unrecaptured 1250 gain, and freed passive losses
- The 2025 SALT cap: $40,000, reduced for high income
- Virginia self-employed: Schedule C, estimates, and the $4,000 Virginia529 deduction
Practice it on a full return
Schedule 2 only makes sense next to the forms that feed it. The freelance designer carries self-employment tax from Schedule SE to line 4, the household employer fills line 9 from Schedule H, and the early retirement withdrawal puts the 10% additional tax on line 8. Browse every practice return, or go back to the interactive Form 1040 to see where lines 3 and 21 land.
FAQ
Who has to file Schedule 2?
Anyone who owes a tax that can't be entered directly on Form 1040: for example the alternative minimum tax, a repayment of excess advance premium tax credit, self-employment tax, household employment taxes, the additional tax on an early IRA or retirement plan distribution, Additional Medicare Tax or the net investment income tax.
Where does self-employment tax go on Form 1040?
It is figured on Schedule SE, line 12, entered on Schedule 2, line 4, and included in the total on Schedule 2, line 21, which goes to Form 1040, line 23. Half of it is deducted on Schedule 1, line 15.
Do I need Form 5329 for an early IRA withdrawal?
Not always. If the only issue is an early distribution, code 1 is correctly shown in box 7 of every Form 1099-R, and no exception applies, you can skip Form 5329: enter 10% of the taxable amount on Schedule 2, line 8, and check the box. If you qualify for an exception, or the code is wrong, file Form 5329.
What changed on the 2025 Schedule 2?
Line 4 now has checkboxes for exemptions from self-employment tax (Form 4361, Form 4029, or another reason) instead of written notes, and line 10, which held the repayment of the first-time homebuyer credit through 2024, is now reserved for future use.